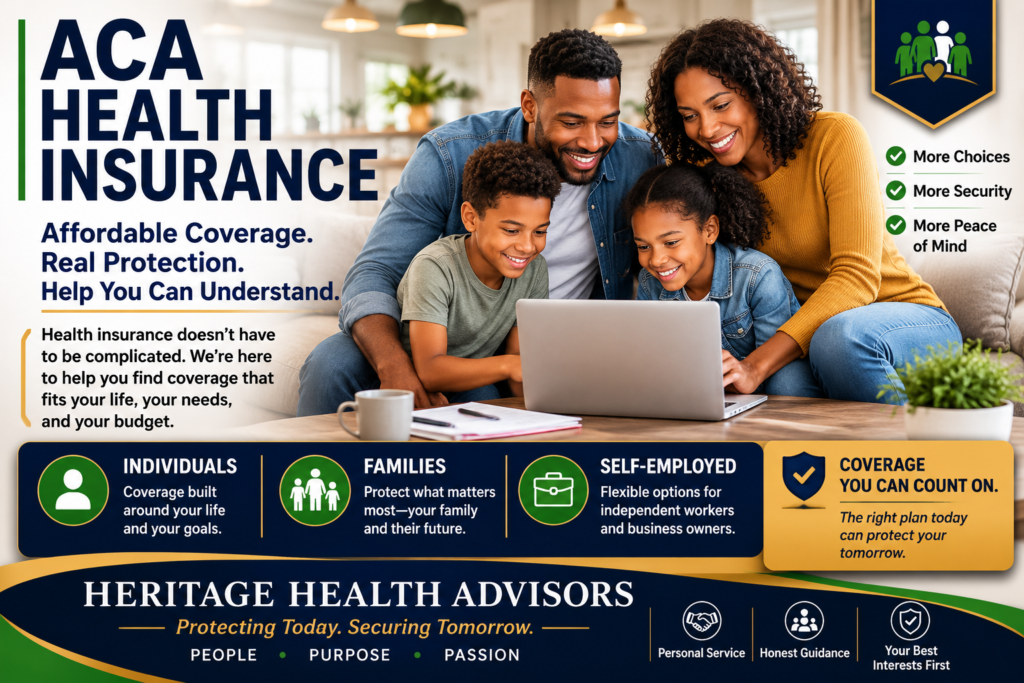
ACA HEALTH INSURANCE
Affordable Coverage. Real Protection. Help You Can Understand.
Health insurance doesn’t have to be complicated.
Whether you’re protecting yourself, your family, or looking for coverage because your situation has changed, Heritage Health Advisors can help you understand your options and find coverage that fits your needs and budget.
INDIVIDUALS • FAMILIES • SELF-EMPLOYED
HERITAGE HEALTH ADVISORS
Protecting Today. Securing Tomorrow.
People • Purpose • Passion
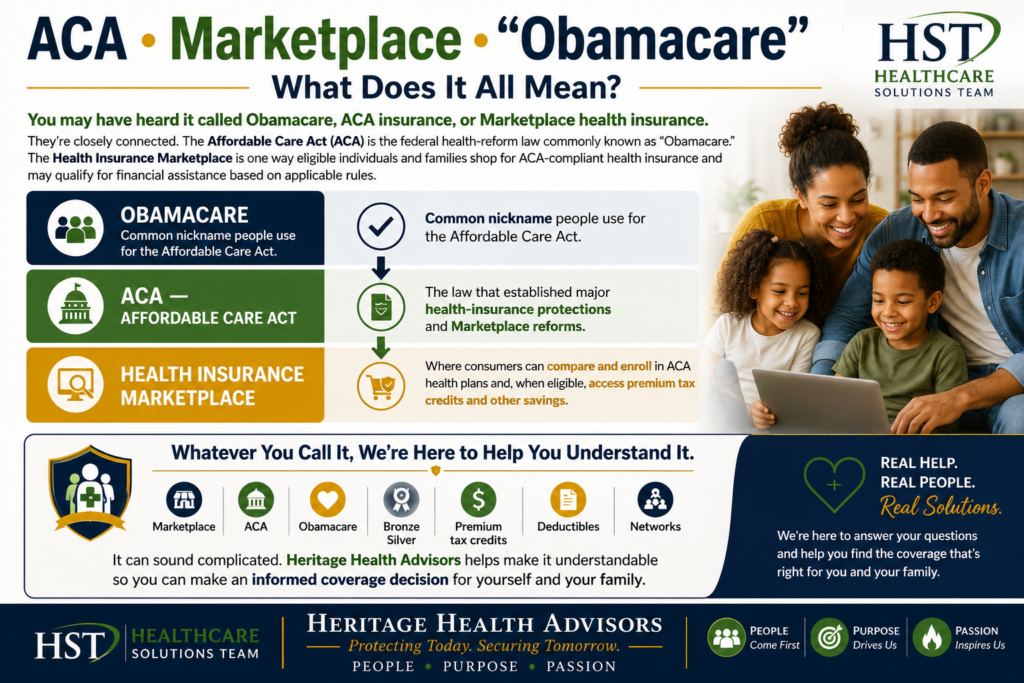
ACA • Marketplace • “Obamacare” — What Does It All Mean?
You may have heard it called Obamacare, ACA insurance, or Marketplace health insurance.
They’re closely connected. The Affordable Care Act (ACA) is the federal health-reform law commonly known as “Obamacare.” The Health Insurance Marketplace is one way eligible individuals and families shop for ACA-compliant health insurance and may qualify for financial assistance based on applicable rules.
OBAMACARE
Common nickname people use for the Affordable Care Act.
ACA — Affordable Care Act
The law that established major health-insurance protections and Marketplace reforms.
HEALTH INSURANCE MARKETPLACE
Where consumers can compare and enroll in ACA health plans and, when eligible, access premium tax credits and other savings.
And then I’d put a Heritage box underneath:
Whatever You Call It, We’re Here to Help You Understand It.
Marketplace. ACA. Obamacare. Bronze. Silver. Premium tax credits. Deductibles. Networks.
It can sound complicated. Heritage Health Advisors helps make it understandable so you can make an informed coverage decision for yourself and your family.
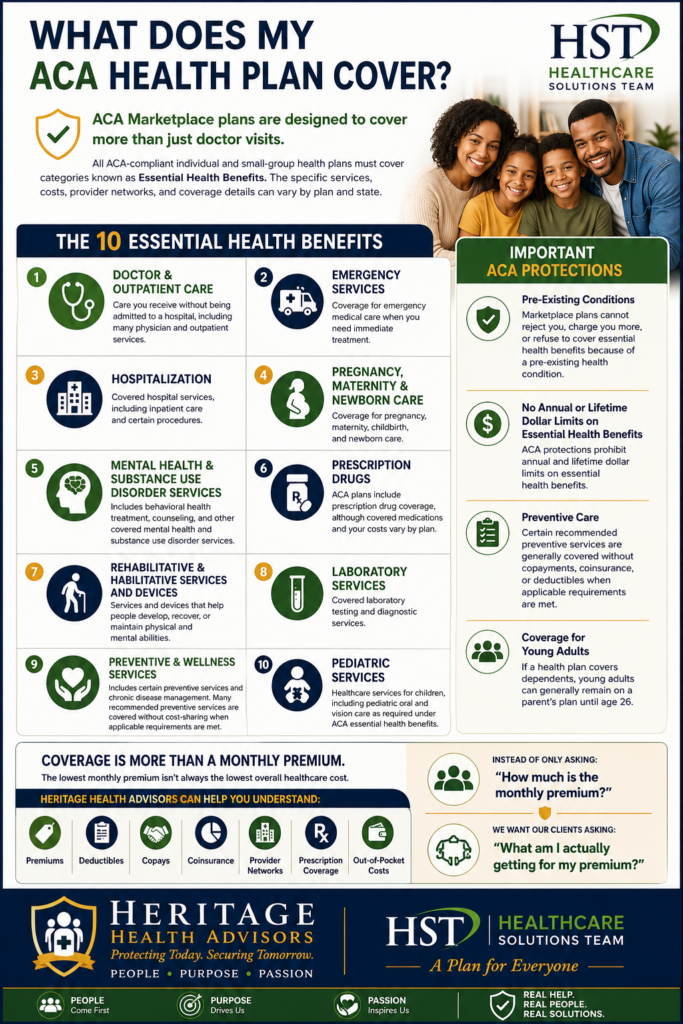
WHAT DOES MY ACA HEALTH PLAN COVER?
ACA Marketplace plans are designed to cover more than just doctor visits.
All ACA-compliant individual and small-group health plans must cover categories known as Essential Health Benefits. The specific services, costs, provider networks, and coverage details can vary by plan and state.
THE 10 ESSENTIAL HEALTH BENEFITS
DOCTOR & OUTPATIENT CARE
Care you receive without being admitted to a hospital, including many physician and outpatient services.
EMERGENCY SERVICES
Coverage for emergency medical care when you need immediate treatment.
HOSPITALIZATION
Covered hospital services, including inpatient care and certain procedures.
PREGNANCY, MATERNITY & NEWBORN CARE
Coverage for pregnancy, maternity, childbirth, and newborn care.
MENTAL HEALTH & SUBSTANCE USE DISORDER SERVICES
Includes behavioral health treatment, counseling, and other covered mental health and substance use disorder services.
PRESCRIPTION DRUGS
ACA plans include prescription drug coverage, although covered medications and your costs vary by plan.
REHABILITATIVE & HABILITATIVE SERVICES AND DEVICES
Services and devices that help people develop, recover, or maintain physical and mental abilities.
LABORATORY SERVICES
Covered laboratory testing and diagnostic services.
PREVENTIVE & WELLNESS SERVICES
Includes certain preventive services and chronic disease management. Many recommended preventive services are covered without cost-sharing when applicable requirements are met.
PEDIATRIC SERVICES
Healthcare services for children, including pediatric oral and vision care as required under ACA essential health benefits.
IMPORTANT ACA PROTECTIONS
Pre-Existing Conditions
Marketplace plans cannot reject you, charge you more, or refuse to cover essential health benefits because of a pre-existing health condition.
No Annual or Lifetime Dollar Limits on Essential Health Benefits
ACA protections prohibit annual and lifetime dollar limits on essential health benefits.
Preventive Care
Certain recommended preventive services are generally covered without copayments, coinsurance, or deductibles when applicable requirements are met.
Coverage for Young Adults
If a health plan covers dependents, young adults can generally remain on a parent’s plan until age 26.
COVERAGE IS MORE THAN A MONTHLY PREMIUM.
The lowest monthly premium isn’t always the lowest overall healthcare cost.
Heritage Health Advisors can help you understand:
Premiums • Deductibles • Copays • Coinsurance • Provider Networks • Prescription Coverage • Out-of-Pocket Costs
So instead of only asking:
“How much is the monthly premium?”
We want our clients asking:
“What am I actually getting for my premium?”
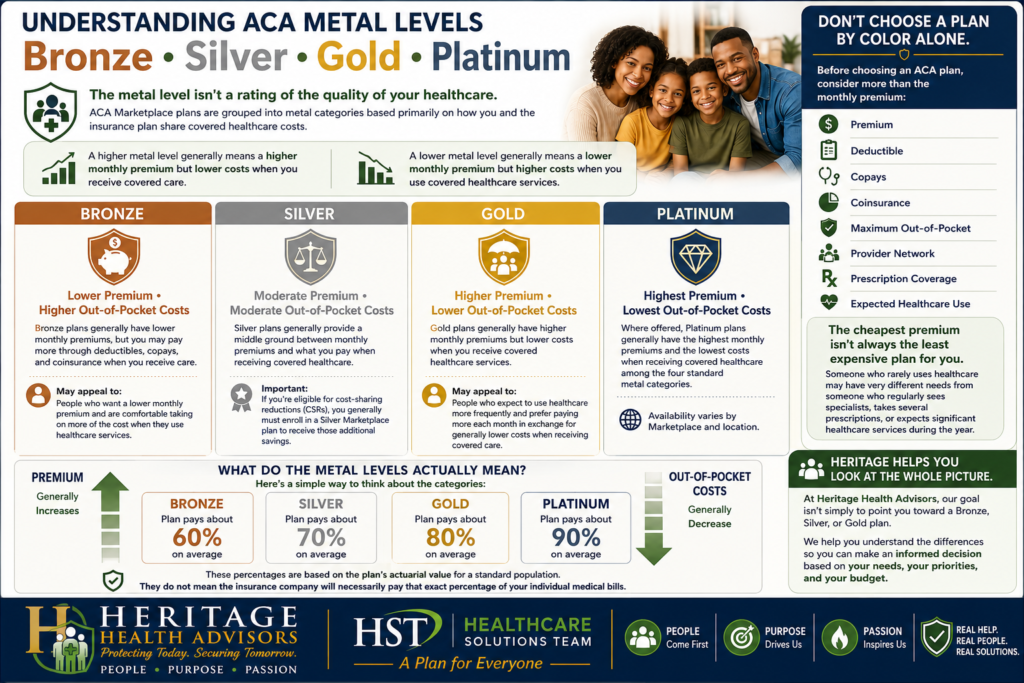
UNDERSTANDING ACA METAL LEVELS
Bronze • Silver • Gold • Platinum
The metal level isn’t a rating of the quality of your healthcare.
ACA Marketplace plans are grouped into metal categories based primarily on how you and the insurance plan share covered healthcare costs.
A higher metal level generally means a higher monthly premium but lower costs when you receive covered care. A lower metal level generally means a lower monthly premium but higher costs when you use covered healthcare services.
BRONZE
Lower Premium • Higher Out-of-Pocket Costs
Bronze plans generally have lower monthly premiums, but you may pay more through deductibles, copays, and coinsurance when you receive care.
May appeal to: People who want a lower monthly premium and are comfortable taking on more of the cost when they use healthcare services.
SILVER
Moderate Premium • Moderate Out-of-Pocket Costs
Silver plans generally provide a middle ground between monthly premiums and what you pay when receiving covered healthcare.
Important: If you’re eligible for cost-sharing reductions (CSRs), you generally must enroll in a Silver Marketplace plan to receive those additional savings.
GOLD
Higher Premium • Lower Out-of-Pocket Costs
Gold plans generally have higher monthly premiums but lower costs when you receive covered healthcare services.
May appeal to: People who expect to use healthcare more frequently and prefer paying more each month in exchange for generally lower costs when receiving covered care.
PLATINUM
Highest Premium • Lowest Out-of-Pocket Costs
Where offered, Platinum plans generally have the highest monthly premiums and the lowest costs when receiving covered healthcare among the four standard metal categories.
Availability varies by Marketplace and location.
WHAT DO THE METAL LEVELS ACTUALLY MEAN?
Here’s a simple way to think about the categories:
BRONZE — Plan pays about 60% on average
SILVER — Plan pays about 70% on average
GOLD — Plan pays about 80% on average
PLATINUM — Plan pays about 90% on average
These percentages are based on the plan’s actuarial value for a standard population. They do not mean the insurance company will necessarily pay that exact percentage of your individual medical bills.
DON’T CHOOSE A PLAN BY COLOR ALONE.
Before choosing an ACA plan, consider more than the monthly premium:
Premium • Deductible • Copays • Coinsurance • Maximum Out-of-Pocket • Provider Network • Prescription Coverage • Expected Healthcare Use
The cheapest premium isn’t always the least expensive plan for you.
Someone who rarely uses healthcare may have very different needs from someone who regularly sees specialists, takes several prescriptions, or expects significant healthcare services during the year.
HERITAGE HELPS YOU LOOK AT THE WHOLE PICTURE.
At Heritage Health Advisors, our goal isn’t simply to point you toward a Bronze, Silver, or Gold plan.
We help you understand the differences so you can make an informed decision based on your needs, your priorities, and your budget.
Don’t just ask, “What’s the cheapest plan?”
Ask, “Which plan makes the most sense for me?”
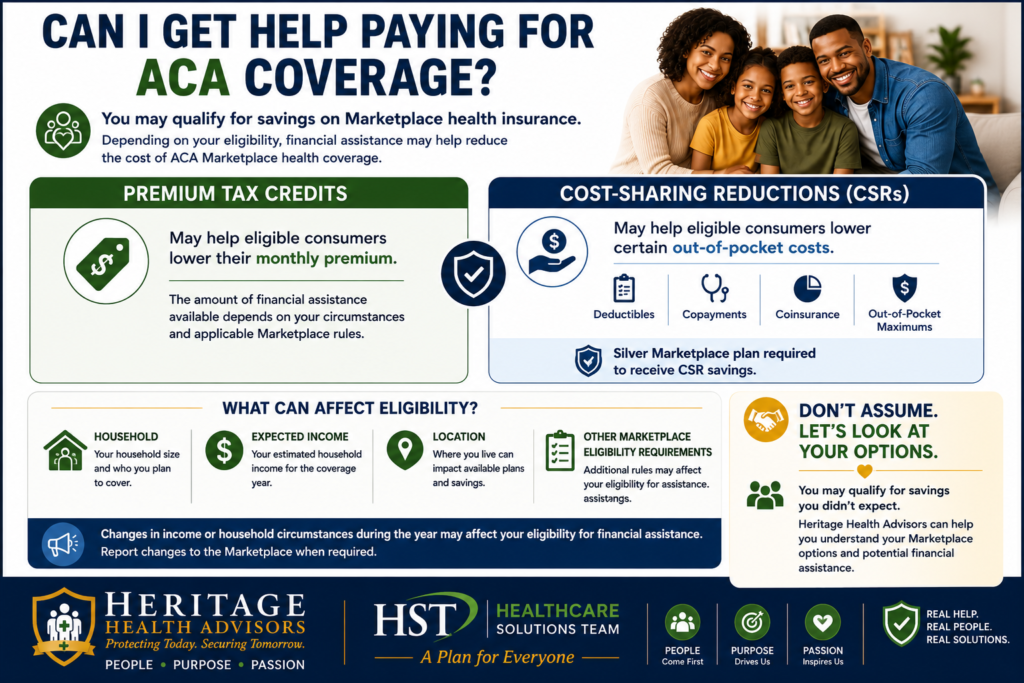
CAN I GET HELP PAYING FOR ACA COVERAGE?
You may qualify for savings on Marketplace health insurance.
Depending on your eligibility, financial assistance may help reduce the cost of ACA Marketplace health coverage.
PREMIUM TAX CREDITS
Premium tax credits can help eligible individuals and families lower the monthly premium they pay for Marketplace health insurance.
The amount of financial assistance available depends on your circumstances and applicable Marketplace rules.
COST-SHARING REDUCTIONS (CSRs)
Cost-sharing reductions can help eligible consumers lower certain out-of-pocket costs when they receive covered healthcare services.
These savings can reduce costs such as:
Deductibles • Copayments • Coinsurance • Out-of-Pocket Maximums
To receive cost-sharing reductions, an eligible consumer must enroll in a Silver Marketplace plan.
YOUR INFORMATION MATTERS
Eligibility for Marketplace savings can depend on factors such as your household, expected household income, where you live, and other eligibility requirements.
Changes in income or household circumstances during the year may affect your eligibility for financial assistance and should be reported to the Marketplace when required.
DON’T ASSUME. LET’S LOOK AT YOUR OPTIONS.
Don’t automatically assume you make too much to qualify for assistance or that Marketplace coverage will be too expensive.
Heritage Health Advisors can help you understand your Marketplace options, available plans, and potential financial assistance based on your individual circumstances.
Real information. Real options. A decision you can understand.
HERITAGE HEALTH ADVISORS
Protecting Today. Securing Tomorrow.
People • Purpose • Passion
In partnership with Healthcare Solutions Team (HST) — A Plan for Everyone
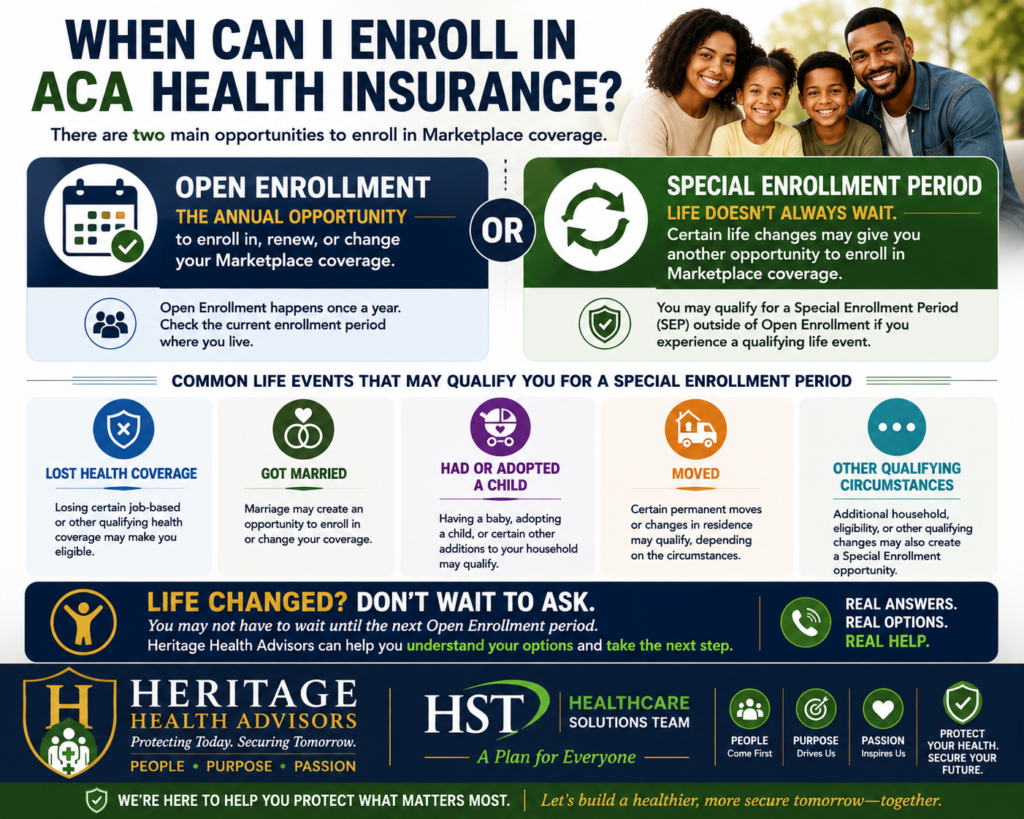
WHEN CAN I ENROLL IN ACA HEALTH INSURANCE?
There are two main opportunities to enroll in Marketplace coverage.
OPEN ENROLLMENT
Open Enrollment is the annual period when eligible consumers can enroll in, renew, or change their ACA Marketplace health insurance.
Enrollment dates can vary by Marketplace and plan year, so it’s important to check the current enrollment period where you live.
SPECIAL ENROLLMENT PERIOD
Life doesn’t always wait for Open Enrollment.
Certain life changes or circumstances may qualify you for a Special Enrollment Period (SEP), allowing you to enroll in or change Marketplace health coverage outside the annual Open Enrollment period.
LIFE CHANGED? YOUR HEALTH COVERAGE MAY BE ABLE TO CHANGE TOO.
Qualifying circumstances may include:
Loss of Qualifying Health Coverage
Losing certain job-based or other qualifying health coverage may make you eligible for a Special Enrollment Period.
Getting Married
Marriage may create an opportunity to enroll in or change Marketplace coverage.
Having or Adopting a Child
Having a baby, adopting a child, or certain other additions to your household may qualify you for a Special Enrollment Period.
Moving
Certain permanent moves or changes in residence may qualify, depending on the circumstances.
Other Qualifying Circumstances
Additional household, eligibility, or other qualifying changes may also create a Special Enrollment opportunity.
DON’T WAIT TO ASK.
Special Enrollment Periods can have time limits, and eligibility depends on the specific circumstances.
If you’ve recently experienced a major life change, don’t automatically assume you have to wait until the next Open Enrollment period.
Heritage Health Advisors can help you understand your options and determine the next steps based on your circumstances.
HERITAGE HEALTH ADVISORS
Protecting Today. Securing Tomorrow.
People • Purpose • Passion
In partnership with Healthcare Solutions Team (HST) — A Plan for Everyone