DISABILITY INSURANCE
YOUR BIGGEST ASSET MAY NOT BE YOUR HOUSE.
It may be your ability to earn a living.
Think about everything your income helps pay for:
Mortgage or Rent • Groceries • Utilities • Car Payments • Insurance • Family Expenses • Everyday Life
Now ask yourself one question:
What happens if the paycheck stops?
An unexpected illness or injury can affect more than your health. If you’re unable to work, it can also affect the income you and your family rely on.
Disability insurance can provide income protection when a covered illness or injury prevents you from working, subject to the terms of the policy.
PROTECT MORE THAN YOUR PAYCHECK.
At Heritage Health Advisors, we’ll help you understand disability coverage, including important considerations such as:
Benefit Amounts • Waiting Periods • Benefit Periods • Definitions of Disability • Policy Limitations
Our goal isn’t simply to sell you a policy.
It’s to help you understand what you’re protecting—and why it matters.
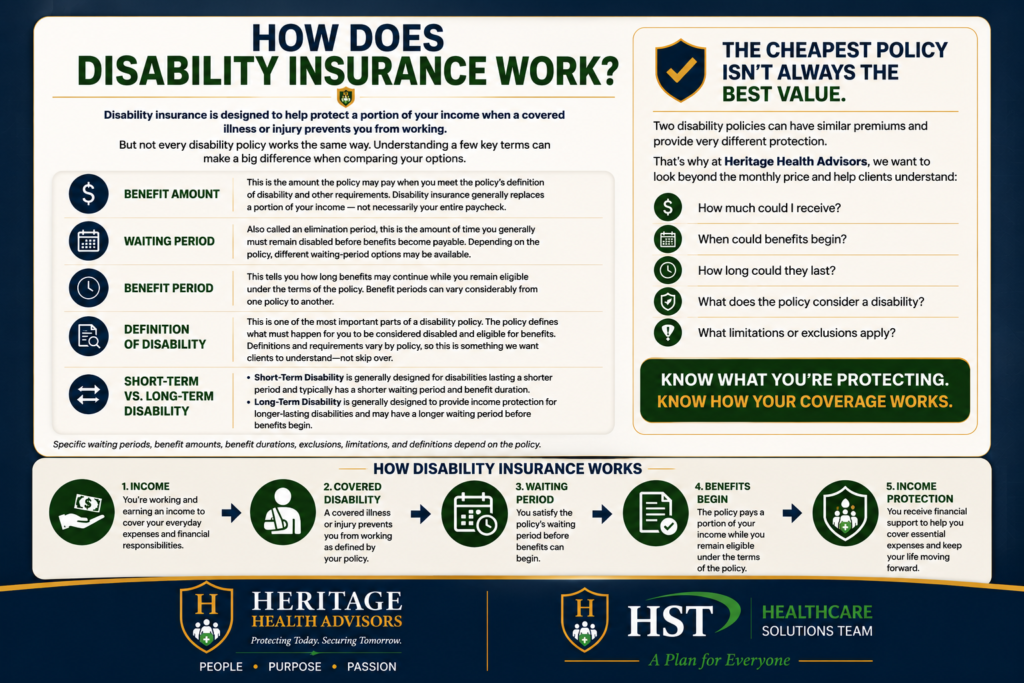
HOW DOES DISABILITY INSURANCE WORK?
Disability insurance is designed to help protect a portion of your income when a covered illness or injury prevents you from working.
But not every disability policy works the same way. Understanding a few key terms can make a big difference when comparing your options.
BENEFIT AMOUNT
This is the amount the policy may pay when you meet the policy’s definition of disability and other requirements.
Disability insurance generally replaces a portion of your income — not necessarily your entire paycheck.
WAITING PERIOD
Also called an elimination period, this is the amount of time you generally must remain disabled before benefits become payable.
Depending on the policy, different waiting-period options may be available.
BENEFIT PERIOD
This tells you how long benefits may continue while you remain eligible under the terms of the policy.
Benefit periods can vary considerably from one policy to another.
DEFINITION OF DISABILITY
This is one of the most important parts of a disability policy.
The policy defines what must happen for you to be considered disabled and eligible for benefits. Definitions and requirements vary by policy, so this is something we want clients to understand—not skip over.
SHORT-TERM VS. LONG-TERM DISABILITY
Short-Term Disability is generally designed for disabilities lasting a shorter period and typically has a shorter waiting period and benefit duration.
Long-Term Disability is generally designed to provide income protection for longer-lasting disabilities and may have a longer waiting period before benefits begin.
Specific waiting periods, benefit amounts, benefit durations, exclusions, limitations, and definitions depend on the policy.
THE CHEAPEST POLICY ISN’T ALWAYS THE BEST VALUE.
Two disability policies can have similar premiums and provide very different protection.
That’s why at Heritage Health Advisors, we want to look beyond the monthly price and help clients understand:
How much could I receive? • When could benefits begin? • How long could they last? • What does the policy consider a disability? • What limitations or exclusions apply?
KNOW WHAT YOU’RE PROTECTING. KNOW HOW YOUR COVERAGE WORKS.
WHO SHOULD CONSIDER DISABILITY INSURANCE?
IF PEOPLE DEPEND ON YOUR INCOME, YOUR INCOME IS WORTH PROTECTING.
Disability insurance isn’t only something to think about if you work in a physically demanding job.
An illness or injury can affect someone’s ability to work in almost any occupation. If your paycheck helps support your lifestyle, your household, or people who depend on you, income protection may be worth considering.
DISABILITY COVERAGE MAY BE WORTH EXPLORING IF YOU ARE:
A Working Professional
Your ability to earn an income may be one of the most valuable financial assets you have.
Self-Employed or a Business Owner
When you’re responsible for generating your own income, being unable to work can create an entirely different financial challenge.
A Primary or Major Household Earner
If your family relies heavily on your paycheck, an extended loss of income could affect the entire household.
Supporting a Family
Mortgage or rent, groceries, utilities, transportation, childcare and other expenses don’t necessarily stop because you’re unable to work.
Building Your Financial Future
An extended interruption in income could affect savings, retirement contributions and other long-term financial goals.
YOU INSURE YOUR HOME.
YOU INSURE YOUR CAR.
WHAT ABOUT THE INCOME THAT PAYS FOR THEM?
Disability insurance isn’t about expecting something bad to happen. It’s about having a plan for your income if the unexpected happens.
Coverage availability, eligibility, benefits, exclusions, limitations and policy terms vary by product and carrier.